The Rise of Cashback Credit Cards: A Deep Dive into Rewards and Future Trends
For years, the allure of a credit card centered on high credit limits. Today, savvy consumers are shifting their focus. The real value lies in rewards – specifically, cashback. Instead of simply borrowing power, people want a return on their spending. This isn’t just a trend; it’s a fundamental change in how we perceive and utilize credit.
Cashback: More Than Just a Percentage
Cashback programs offer a percentage of your spending back, typically as statement credit, direct deposit, or gift cards. But the landscape is becoming increasingly nuanced. The simple 1% across the board is fading, replaced by tiered systems, category bonuses, and personalized offers. A recent study by CreditCards.com found that the average cashback card now offers between 1.5% and 2% back on purchases.
Spotlight on Leading Cashback Programs: A Regional View
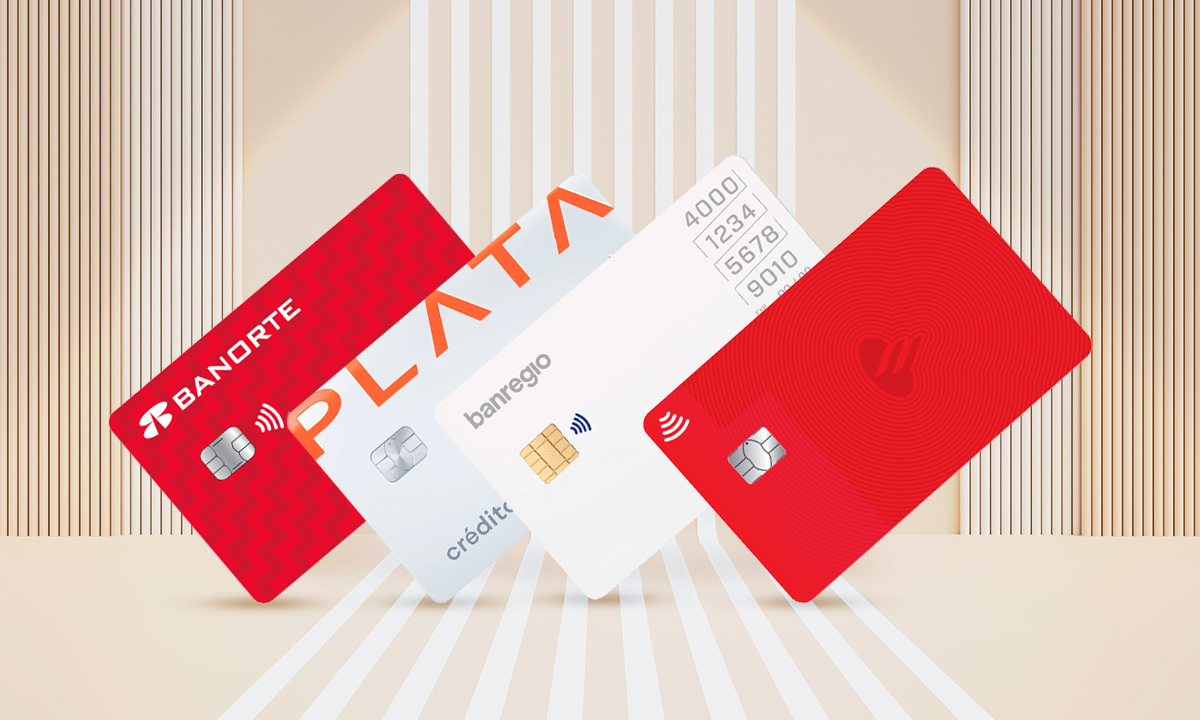
Recent analysis, like that conducted by EL CEO, highlights the competitive landscape. Santander’s limited-time 15% cashback on digital purchases (with conditions) demonstrates a willingness to offer aggressive incentives, albeit temporarily. This tactic is becoming common – limited-time promotions designed to attract new customers and encourage digital adoption. Banregio’s tiered approach (2% online, 1% in-store, 1% referrals) caters to diverse spending habits. Banorte’s simple 1% plus bonuses on gas and dining provides straightforward value. Fintechs like Plata Card and DiDi Card are innovating with customizable categories, allowing users to maximize rewards where they spend the most.
The Fintech Disruption: Personalization and Flexibility
Platforms like Plata Card and DiDi Card represent a significant shift. They’re moving away from one-size-fits-all rewards programs and embracing personalization. This is powered by data analytics – understanding where consumers spend their money and offering higher cashback rates in those categories. This trend is likely to accelerate, with AI playing a larger role in dynamically adjusting rewards based on individual spending patterns. Consider the example of Revolut, a UK-based fintech, which offers personalized cashback offers through its app based on partnerships with retailers.
Beyond Traditional Cashback: Emerging Reward Structures
While cashback remains dominant, other reward structures are gaining traction:
- Points Systems: Often tied to travel or specific retailer ecosystems (think airline miles or hotel points).
- Tiered Rewards: Spending thresholds unlock higher cashback rates or exclusive perks.
- Crypto Rewards: A growing number of cards offer rewards in cryptocurrency, appealing to a tech-savvy demographic.
The Role of Buy Now, Pay Later (BNPL) and Cashback
The integration of cashback with Buy Now, Pay Later (BNPL) services is a developing area. Some BNPL providers are beginning to offer cashback rewards on purchases, further incentivizing their use. This creates a complex interplay between credit cards, BNPL, and rewards programs. A recent report by Statista projects the BNPL market to reach $335 billion by 2027, indicating significant growth potential for integrated reward systems.
Ualá, HSBC 2Now, and the Importance of Accessibility
The success of cards like Ualá (with its supermarket focus) and HSBC 2Now (requiring a higher income) highlights the importance of accessibility. Cards tailored to specific demographics or spending habits can be highly effective. However, excluding segments of the population limits potential growth. The future will likely see more cards designed for underserved markets, offering relevant rewards and lower barriers to entry.
Future Trends: What to Expect in the Cashback Landscape
Hyper-Personalization Driven by AI
Expect AI to become even more integral in tailoring cashback offers. Algorithms will analyze spending data in real-time, predicting future purchases and proactively offering rewards in relevant categories.
The Rise of “Cashback as a Service”
We may see the emergence of platforms that allow consumers to aggregate cashback rewards from multiple cards and programs into a single account, simplifying the process and maximizing savings.
Integration with Loyalty Programs
Cashback programs will increasingly integrate with existing loyalty programs, creating a seamless rewards experience across multiple brands and retailers.
Increased Focus on Sustainability Rewards
Consumers are becoming more environmentally conscious. Cards offering cashback for sustainable purchases (e.g., electric vehicle charging, organic groceries) are likely to gain popularity.
FAQ: Your Cashback Questions Answered
Q: What is the best cashback credit card?
A: There’s no single “best” card. It depends on your spending habits and financial situation.
Q: How does cashback get paid out?
A: Typically as a statement credit, direct deposit, or gift cards.
Q: Are there any limits to how much cashback I can earn?
A: Yes, many cards have spending caps or quarterly limits on cashback earnings.
Q: Does using a cashback card affect my credit score?
A: Responsible use (paying on time and keeping balances low) can actually *improve* your credit score.
Did you know? Many cashback cards offer introductory bonuses – a significant amount of cashback earned after spending a certain amount within the first few months.
Pro Tip: Always read the fine print of any cashback program to understand the terms and conditions, including any limitations or exclusions.
Want to learn more about maximizing your credit card rewards? Explore more articles on EL CEO and share your thoughts in the comments below!
Worth a look