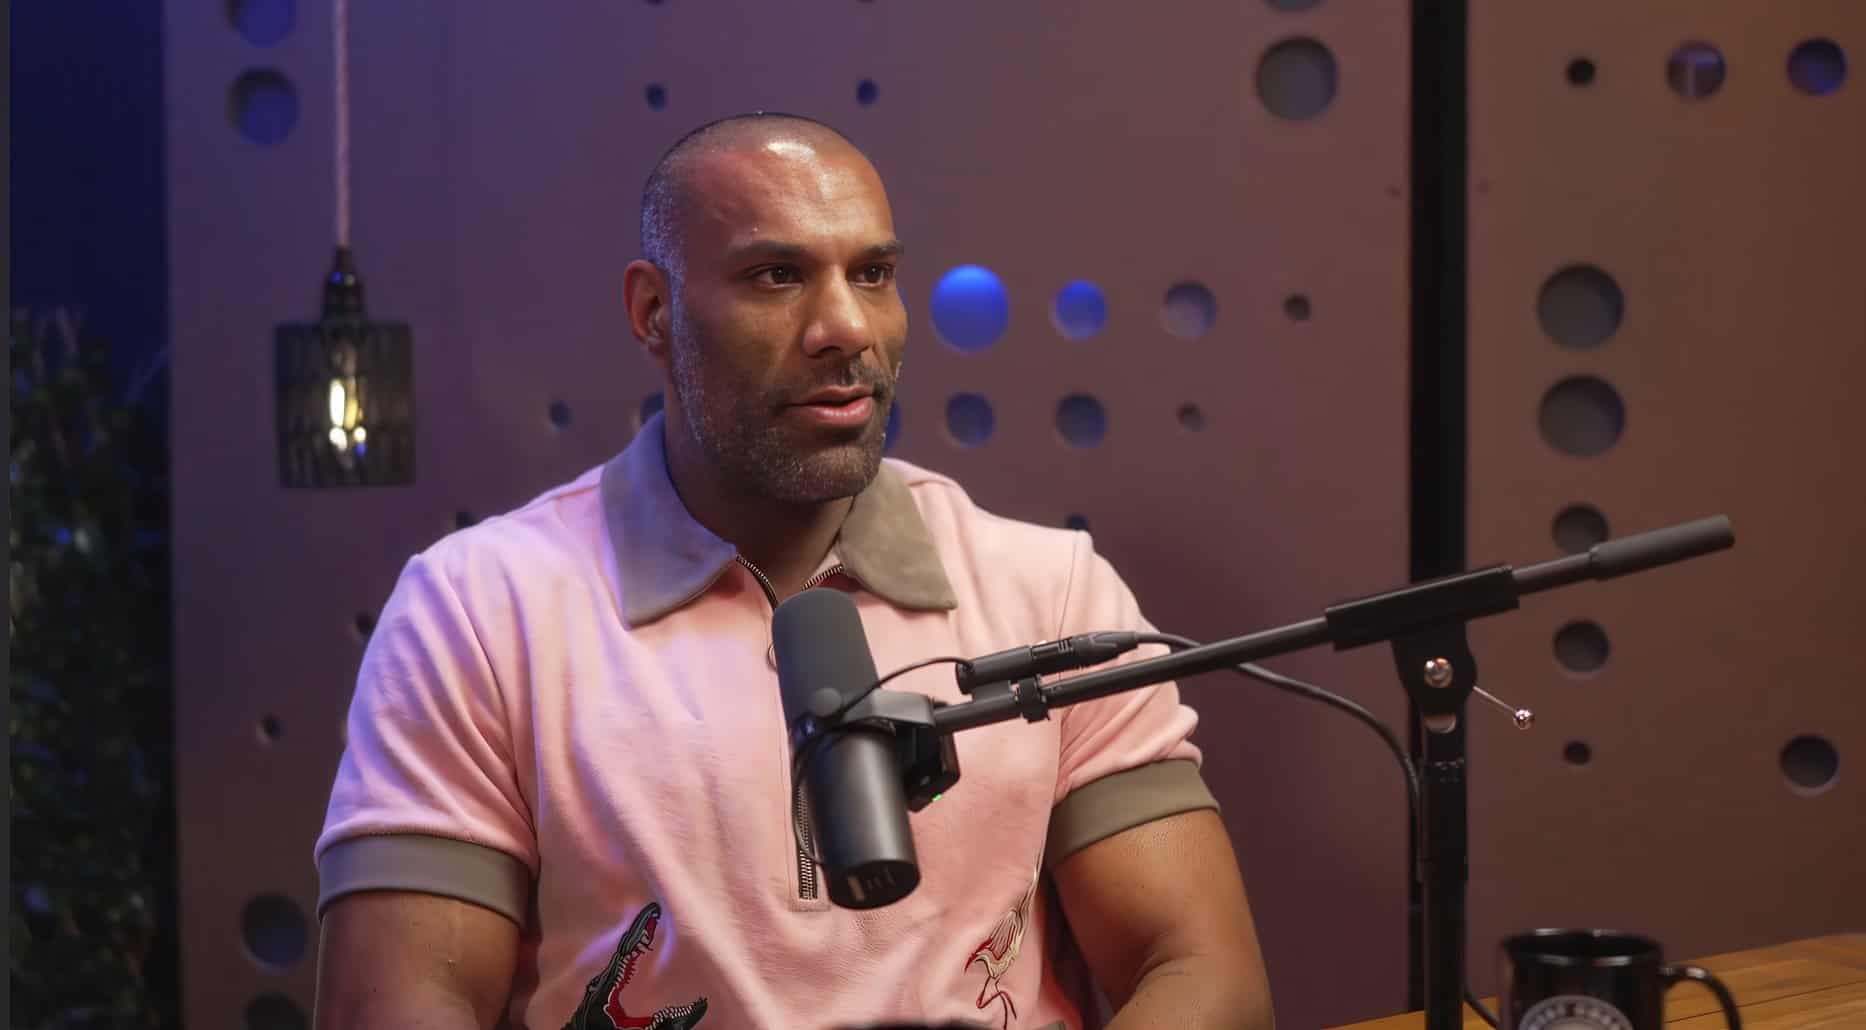
Jinder Mahal Leads Charge for Wrestler Financial Literacy: A Look at Retirement Planning in the Independent Circuit
Former WWE Champion Raj Dhesi, known to fans as Jinder Mahal, is taking a proactive step towards addressing a critical issue in professional wrestling: financial security. He recently announced a series dedicated to financial literacy for wrestlers, beginning with a detailed breakdown of retirement account options on Instagram. This initiative comes at a time when the conversation around wrestler compensation and long-term financial planning is gaining momentum.
The Independent Contractor Reality
A core message from Dhesi’s campaign is the responsibility wrestlers have for their own financial futures. Unlike traditional employees, professional wrestlers are often classified as independent contractors, meaning they are responsible for establishing and funding their own retirement plans. This applies regardless of whether they compete in major promotions like WWE, AEW, or TNA, or on the independent circuit.
“There’s a common misconception that wrestlers don’t have retirement accounts. It’s complete BS,” Dhesi stated in his Instagram video. “When you’re an independent contractor, you will not be receiving a company match. The company doesn’t establish your retirement accounts. You’re responsible for it.”
Retirement Account Options for Wrestlers
Dhesi outlined two primary retirement account options available to US-based wrestlers: Roth IRAs and Solo 401(k)s.
- Roth IRA: Funded with after-tax dollars, offering tax-free growth and withdrawals in retirement. Although, annual contribution limits and income restrictions apply.
- Solo 401(k): Allows contributions with pre-tax income, reducing current taxable income, with tax-deferred growth until withdrawal. Contribution limits are significantly higher than Roth IRAs, enabling more substantial savings.
“Whatever you contribute into your Solo 401(k) for the year, you secure as a tax write-off. It comes off your gross income, lowers your tax liability for the year,” Dhesi explained. He encourages wrestlers to utilize both account types and consult with an investment professional.
Pro Tip: Don’t overlook the power of compounding interest. Starting early, even with small contributions, can significantly impact your retirement savings.
A Growing Concern: Wrestler Financial Security
Dhesi’s initiative arrives amidst increasing discussion about the financial well-being of wrestlers after their careers end. The lack of employer-sponsored benefits – retirement plans, health insurance, and other protections – for independent contractors is a significant concern. Veterans like Shane Douglas have recently highlighted this issue, suggesting that the industry has the capacity to provide a stronger safety net for its performers.
Future Trends in Wrestler Financial Planning
Several trends suggest a growing awareness and potential for change in how wrestlers approach financial planning:
- Increased Financial Literacy: More wrestlers are actively seeking financial education, as demonstrated by Dhesi’s initiative. This trend is likely to continue, driven by social media and peer-to-peer learning.
- Unionization Efforts: Whereas challenging, ongoing discussions about wrestler unionization could lead to collective bargaining for benefits, including retirement plans.
- Promotion-Sponsored Options: Some promotions may begin offering voluntary retirement plans or financial advisory services to their independent contractors as a way to attract and retain talent.
- Financial Planning Services Tailored to Wrestlers: A niche market for financial advisors specializing in the unique challenges faced by professional wrestlers is likely to emerge.
Did you understand? The average professional wrestling career is relatively short, often lasting less than 10 years, making diligent financial planning even more crucial.
FAQ: Wrestler Retirement Planning
- Q: Are wrestlers eligible for Social Security?
A: Yes, if they meet the eligibility requirements based on their earnings history. - Q: What is the difference between a Roth IRA and a Solo 401(k)?
A: A Roth IRA uses after-tax dollars with tax-free withdrawals, while a Solo 401(k) uses pre-tax dollars with tax-deferred growth. - Q: Should I consult a financial advisor?
A: Yes, a financial advisor can provide personalized guidance based on your individual circumstances.
Raj Dhesi’s efforts represent a positive step towards empowering wrestlers to take control of their financial futures. As the conversation around financial security continues, You can expect to see further innovation and support for wrestlers navigating the complexities of retirement planning.
Wish to learn more about financial planning? Explore resources from the Internal Revenue Service and consider consulting with a qualified financial advisor.
Keep reading