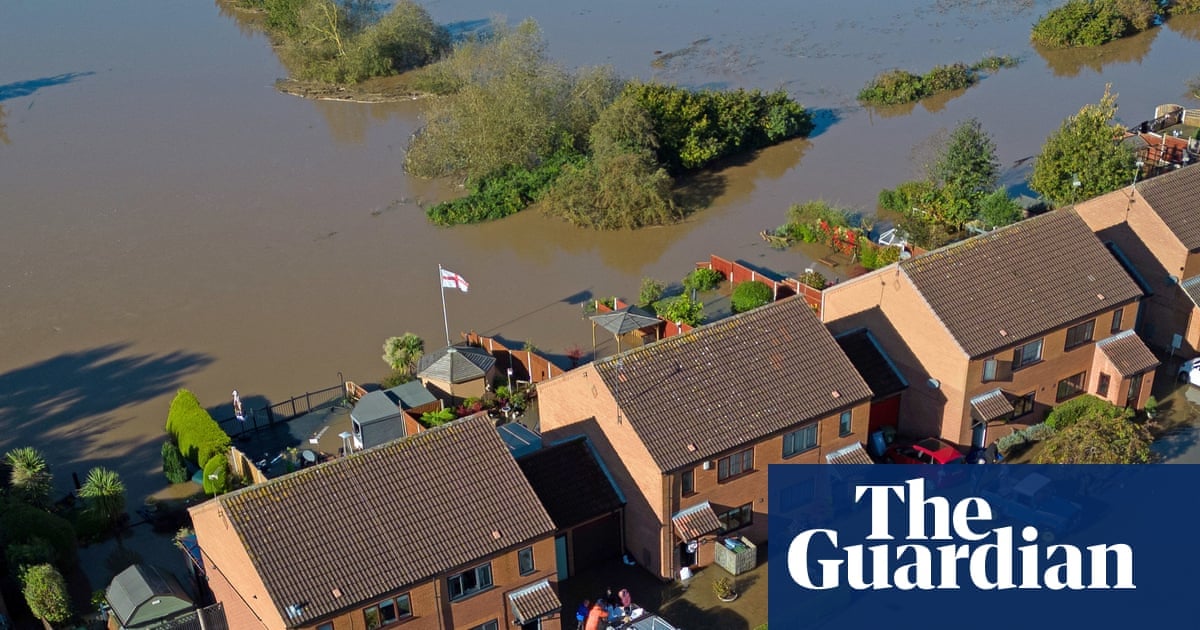
Aviva chief executive Amanda Blanc has warned that homes being built in flood-risk areas of England could become uninsurable in the future, pointing to rising climate pressures and planning decisions that clash with mounting environmental hazards.
Britain’s insurance sector is sounding a sharp alarm over housing development in zones vulnerable to rising waters. Amanda Blanc, the chief executive of Aviva, stated publicly that England is for sure
building residential properties that may eventually lose access to standard insurance coverage.
The warning highlights a growing collision between national housing targets and the physical realities of climate change. According to Environment Agency data, roughly 6.3 million homes and businesses across England already face flood risks from rivers, the sea, or surface water. That exposure affects about one in five properties, a share projected to climb to one in four by the middle of the century.
Aviva Research Tracks New Construction in Vulnerable Zones
Aviva’s internal analysis reveals that development in hazard-prone areas continues. The company’s published figures indicate that 43,937 homes built between 2022 and 2024—representing one in nine new residential properties—sit at medium or high risk of flooding. A broader look counting any level of flood exposure captured 101,657 newly built homes over those three years.

To map these figures, analysts combined Ordnance Survey AddressBase records with Environment Agency constituency-level flood data during research conducted across December 2025 and January 2026. The findings project that 15 percent of homes constructed from 2022 through 2024 will face medium or high flood exposure by 2050 as severe weather intensifies.
Blanc noted that if current development patterns persist, another 115,000 new homes will rise in flood zones over the coming decade, adding to the 110,000 properties built in similar areas over the past ten years.
“That doesn’t seem to me to make sense. We need to think about where those homes are being built.”
Amanda Blanc, Chief Executive of Aviva, via BBC
Insurance contracts depend on shared risk within a pool where losses affect only a portion of policyholders. Blanc explained that insuring properties with a near certainty of flooding becomes very difficult. If a property cannot get insurance cover or it is prohibitively expensive to insure, homeowners face the financial burden directly, which can severely impair their ability to secure mortgages or sell the property.
Government Planning Proposals and Property Resilience Measures
In response to the insurance sector’s concerns, a spokesperson for the Department for Environment, Food and Rural Affairs pointed to ongoing legislative and financial efforts to safeguard communities.
“We’ve put a record amount of investment into protecting nearly 900,000 properties against billions of pounds of flooding damage. Meanwhile our planning proposals will help ensure that housebuilding will not go ahead in areas that are at risk of flooding, helping us to build 1.5 million homes without compromising on safety.”
Spokesperson, Department for Environment, Food and Rural Affairs, via BBC News
Alongside site selection, Blanc argues that builders must alter how individual structures are designed when development borders vulnerable zones. Modifications can make a building more or less vulnerable to flood. Practical steps include installing bricks equipped with self-closing air vents, replacing wooden furniture with stainless steel kitchens in ground-floor areas, and placing electrical plug points halfway up walls rather than near the floor.
Historical context shows that severe weather events are becoming more frequent. Following the stormy winter of 2023-24, the Met Office estimated that record-breaking wet winters had shifted from once-in-80-year occurrences to once-in-20-year events under current levels of global warming.
Worth a look