Australian consumers may still encounter card payment surcharges at the checkout following an October 1, 2026, ban, as business lobby groups warn that many smaller shops, particularly those operated by migrants, remain unprepared for the new rules. The Reserve Bank confirmed the sweeping regulatory changes in March, aiming to eliminate credit and debit card fees and save consumers an estimated $1.6 billion annually.
Small Business Confusion and Compliance Challenges
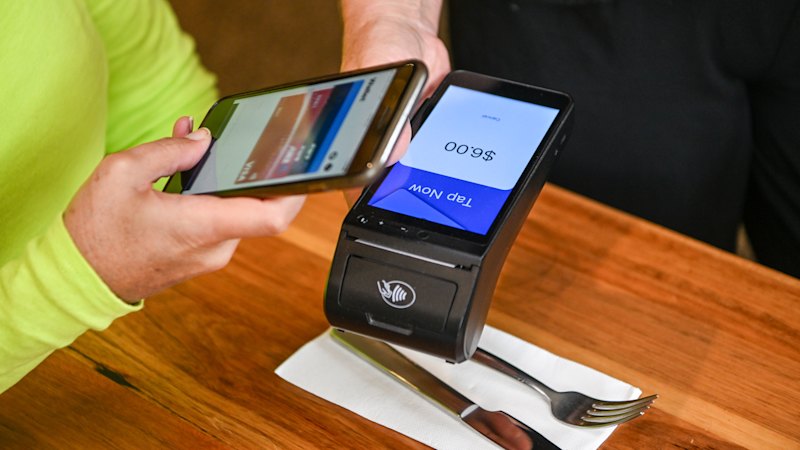
While major banks and national chains have adjusted to the payments ecosystem overhaul, independent merchants face significant hurdles. Brian Laul, founder of the Australian Multicultural Community and Business Chamber, stated that shops run by migrants and non-native English speakers are at particular risk of unwittingly breaching the surcharge ban. “A lot of businesses are quite ill-prepared, from what I’m hearing. There are still lots of queries about how it will work at the checkout,” Laul said. Restaurant and Catering Industry Association CEO Wes Lambert noted that while modern terminals integrated with point-of-sale systems might automatically drop surcharge line items, older terminals requiring manual entry are unlikely to update, leaving businesses at risk of accidentally continuing the practice.
Merchant Infrastructure and Payment Provider Enforcement
Enforcement of the ban falls outside the jurisdiction of the Reserve Bank or the Australian Competition and Consumer Commission. Instead, card networks including Visa, Mastercard, Eftpos, American Express, UnionPay, and PayPal, alongside payment processors like Square, Tyro, Stripe, and participating banks, carry the responsibility for enforcement. These providers were mandated to disable surcharge functions on terminals they control by the October deadline. Meanwhile, business owners like jewellery maker Iris Isaacs, who runs the online store inSync design, report that absorbing these costs or switching payment gateways remains difficult amid rising input costs for gold, manufacturing, and shipping.
Broader Impacts on Banking Rewards and Government Payments
The regulatory shift has already reshaped the broader financial sector. Major banks scaled back credit card sign-on bonuses and rewards point earning rates in response to lower caps on interchange fees—the costs merchants pay to accept card transactions that traditionally funded rewards perks. The Australian Taxation Office removed credit cards entirely as a payment method. The agency stated that only 2.3 per cent of tax payments in the 2024 financial year relied on credit cards, primarily used by high net worth individuals or major organisations, and declared it inappropriate to transfer merchant fees to the wider community.
Frequently Asked Questions About the Card Surcharge Ban
When did the card payment surcharge ban take effect?
The ban came into effect on October 1, 2026, following confirmation by the Reserve Bank in March.
Who is responsible for enforcing the surcharge ban?
Card networks such as Visa, Mastercard, and Eftpos, along with payment providers and banks, are responsible for enforcing the ban and disabling surcharge functions on their terminals.
Why are some small businesses still charging card fees?
Business lobby groups report that many smaller shops and migrant-run businesses lack the technical infrastructure or awareness to update older terminals, leading to accidental non-compliance.
How does the ban affect ATO payments?
The Australian Taxation Office removed credit cards as a payment method ahead of the ban, citing that it is inappropriate to transfer merchant fee costs to the community.