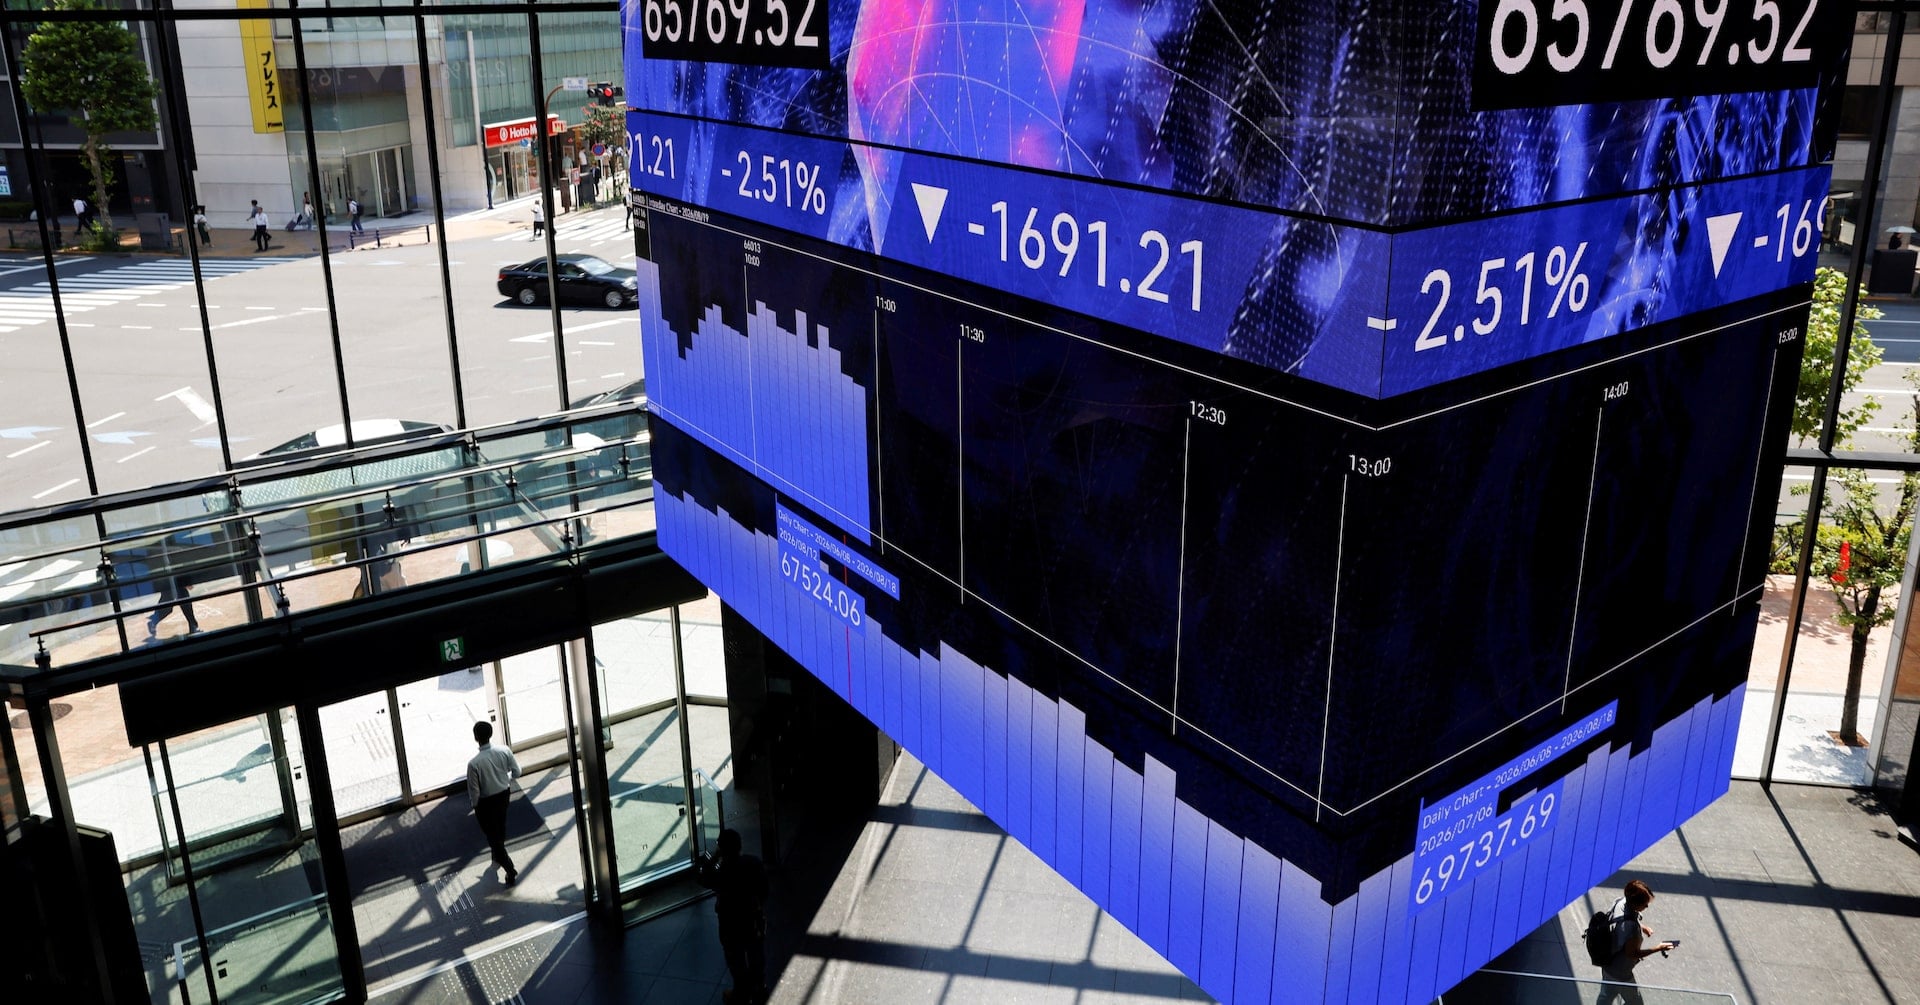
Global financial markets faced heightened volatility on October 2, 2026, as Asian shares retreated following sharp swings in U.S. bond and currency markets. Investors weighed a widening military buildup in the Gulf against upcoming U.S. employment data that could influence the Federal Reserve’s next interest rate decisions.
US Treasury Yields Retreat from Multi-Decade Highs
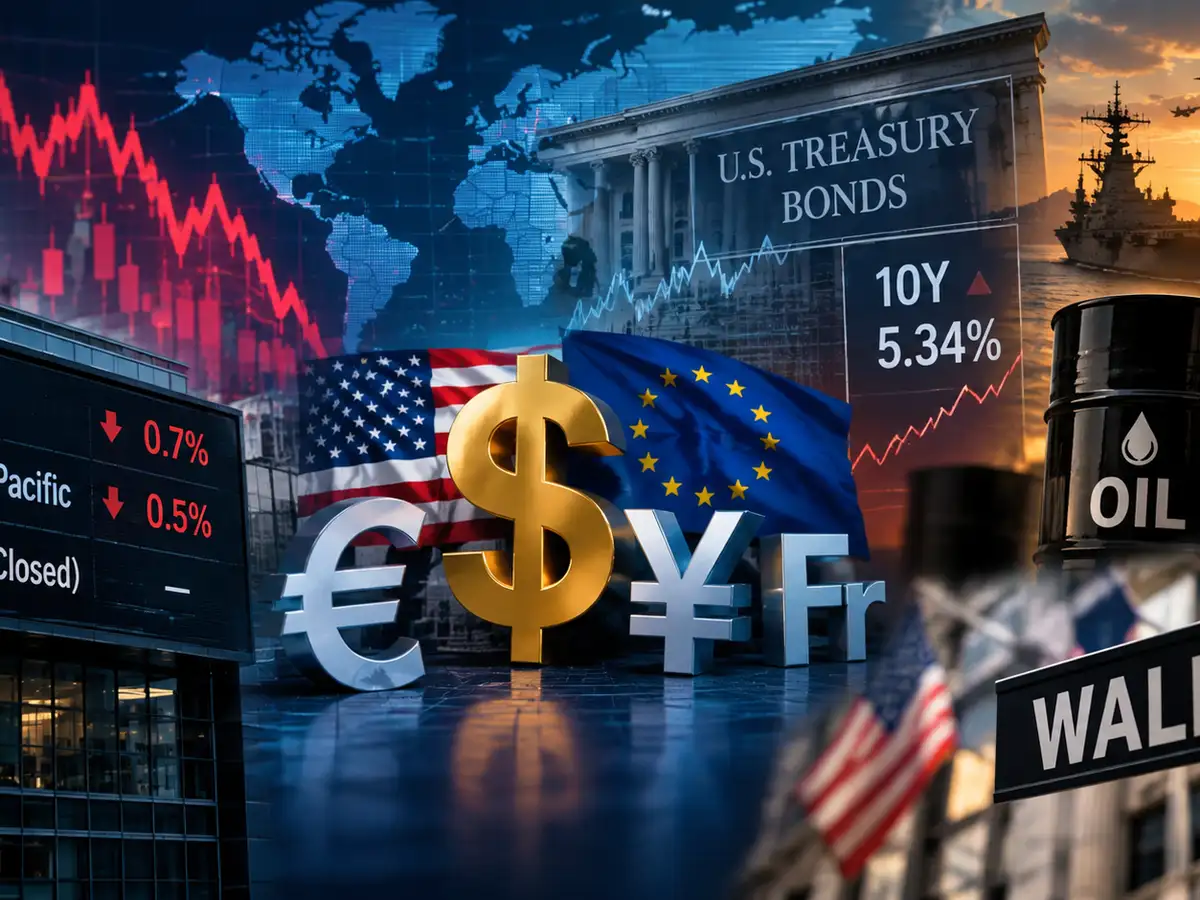
Bond market volatility remained the central focus for traders as U.S. Treasury yields retreated from multi-decade highs. The benchmark 10-year U.S. Treasury yield sat around 5.24% in early trading, pulling back from a 24-year high of 5.34% reached after capping its biggest quarterly rise in 32 years. T. Rowe Price portfolio manager David Clewell noted in a commentary that the 5% threshold serves as an important psychological threshold
for investors navigating rising government debt and inflationary pressures driven by energy shocks.
During this period, benchmark 10-year U.S. Treasury yields touched their highest levels since 2002 after capping their largest quarterly increase in 32 years. ING Bank analysts stated in a weekly commentary that ongoing pressure from elevated energy prices and inflation is expected to continue pushing U.S. 10-year yields upward. Meanwhile, government bond yields remained elevated as bond investors demanded higher compensation to offset increasing risks and uncertainties, which included growing inflationary pressures from an energy shock driven by war involving Iran and rising U.S. government debt.
Pepperstone head of research Chris Weston highlighted the significance of wage data in an environment where inflation remains at the forefront of central bank policy.
“With the Fed now myopically focused on inflation and price pressures, a hot wages print could prove particularly influential for US rates, Treasuries and the USD.”
Chris Weston, head of research at Pepperstone
Markets currently price in a 25% probability that the Fed will raise interest rates again in October, down significantly from 69% the previous week after policymakers signaled a desire for additional economic data.
French Fiscal Concerns Push Bond Yields Higher
While U.S. Treasuries found some stability, European markets absorbed severe pressure from fiscal concerns in France. The spread between French and German sovereign bond yields widened past 140 basis points—reaching its widest level since 2012—as French yields hit 14-year highs.
The euro slid as far as $1.1250, marking its lowest level since May 2025, while also weakening notably against the Japanese yen and the Swiss franc.

Military Deployments Keep Oil Prices Elevated
Stock indexes across the Asia-Pacific region reflected the broader crosscurrents.
Energy markets mirrored the geopolitical tensions as the U.S. military deployed additional troops and another aircraft carrier to the Middle East. Although oil prices dipped slightly in early Friday trading—West Texas Intermediate crude slipping 0.4% to $92.46 a barrel and Brent crude losing 0.7% to $101.56 a barrel—prices remained elevated well above pre-conflict levels seen in late February. Compounding supply concerns, China suspended its exports of oil products, leaving traders to monitor whether global fuel shortages will intensify.