Asian equity markets remained mixed on Friday as a relentless global bond selloff pushed long-dated U.S. Treasury yields to multi-decade highs, increasing worldwide borrowing costs and threatening equity valuations. The market volatility comes as investors weigh persistent inflation fears and the limited breakthroughs from a summit between U.S. President Donald Trump and Chinese President Xi Jinping.
Treasury Yields Surge to Historic Peaks
The benchmark 10-year U.S. Treasury yield rose to 5.1915% on Friday, following a surge of 20 basis points over two days to reach a 19-year peak of 5.2251%. According to Reuters, this represents the largest two-day gain since April of last year, when markets were spooked by President Trump’s Liberation Day tariffs.
Pressure extended to longer-dated debt, with 30-year U.S. bond yields climbing to 5.4805% after hitting 5.5016%, the highest level since 2004. These rising yields have pushed U.S. mortgage rates to 7%, a move that is hamstringing the housing market. At the shorter end of the curve, 2-year yields hovered near a two-year high at 4.9035%.
Nigel Green, CEO of financial advisory firm deVere Group, warned that once risk-free rates in the U.S. exceed 5%, every asset class—including property, private credit, and emerging market debt—must justify its price against that benchmark.
Asian Markets React to Bond Selloff
The selloff in U.S. government bonds spilled over into Asian debt markets. Japan’s 10-year government bond yields rose 4 basis points to 3.115%, marking the highest level since 1996. Australia’s 10-year government bond yields also increased by 4 basis points to 5.408%.
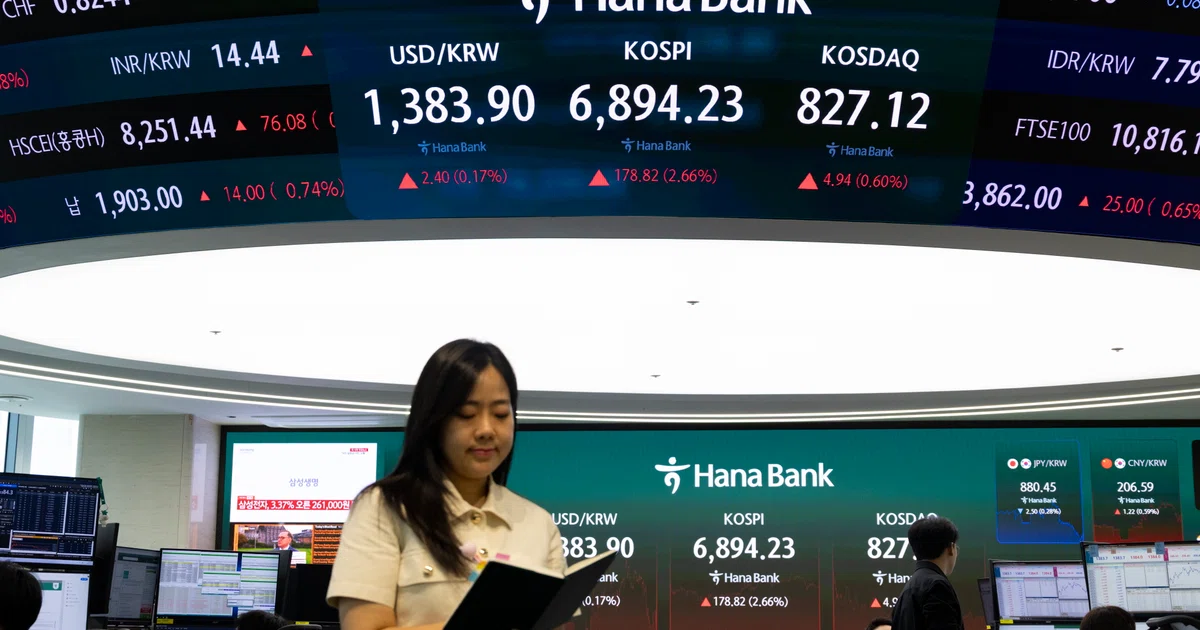
Equity performance across Asia was fragmented, partly due to regional holidays in mainland China, Taiwan, and South Korea. Key market movements included:
- Japan: The Nikkei rose 1% (some reports indicated gains up to 1.3%), supported by technology shares and a weaker yen.
- Hong Kong: The Hang Seng index skidded 1%, with some reports citing a decline of nearly 1.5%.
- Australia: Resources-heavy shares fell 0.6%.
- Other: Singapore and India indices each traded 0.1% higher.
Inflation Fears and Fed Tightening Bets
Inflation concerns have been revived by oil prices returning above $100 a barrel. Brent crude reached near $105, bolstered by a Houthi missile attack on Saudi Arabia. While Brent eased 0.8% to $105.75 a barrel on Friday, the surge has increased bets on further Federal Reserve rate hikes.

The Federal Reserve raised borrowing costs last week for the first time in more than three years to a range of 3.75% to 4%. Fed Governor Michael Barr stated that further hikes are likely needed to reach the 2% inflation target. Fed funds futures now imply a 71% chance of another rate hike next month, up from 53% earlier in the week. Traders anticipate more than 90 basis points of tightening remain in this cycle.
This hawkish shift is rippling globally. Norway’s Norges Bank raised rates Thursday, and Sweden’s Riksbank signaled it would likely follow by year-end. Mexico’s Banxico held rates steady but abandoned its previous guidance for a prolonged pause.
Trump-Xi Summit and Geopolitical Tensions
President Donald Trump and President Xi Jinping met in Washington on Thursday. U.S. Treasury Secretary Scott Bessent stated the two sides agreed to extend their trade truce by two months to allow more time for negotiations regarding technology restrictions, rare-earth supplies, tariffs, and Chinese purchases.
Despite the extension, Reuters reported scant evidence of breakthroughs on thorny issues including AI, Taiwan, and the war with Iran. Simultaneously, markets are monitoring reports that the U.S. and Iran are exploring a phased path to reopen the Strait of Hormuz, though Iranian President Masoud Pezeshkian previously stated navigation would not be allowed while sanctions and a U.S. blockade remain.