Pakistan’s Super Tax Ruling: A Watershed Moment for Fiscal Authority
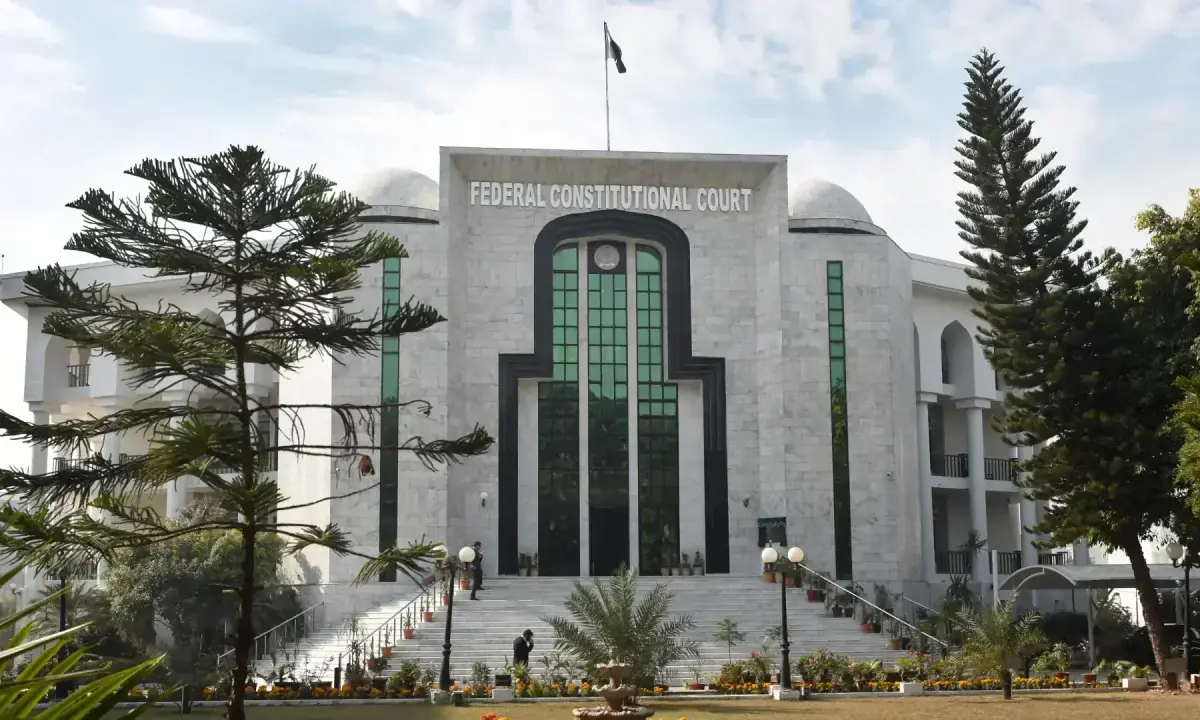
Islamabad witnessed a landmark decision this week as the Federal Constitution Court (FCC) unequivocally upheld the validity of the “super tax” levied on high-income earners and certain sectors. This ruling, stemming from challenges to Sections 4-B and 4-C of the Income Tax Ordinance, 2001, isn’t just a win for the government; it’s a significant reaffirmation of Parliament’s power to legislate on taxation – a power that had been increasingly questioned in recent years.
The Core of the Ruling: Parliament’s Prerogative
The FCC’s decision effectively dismantles arguments that the super tax constituted retrospective taxation, double taxation, or discriminatory practices. The three-member bench, led by Chief Justice Aminuddin Khan, firmly established that courts should interpret tax laws, not rewrite them. This is a crucial distinction. The court’s stance clarifies that determining tax slabs, rates, and overall fiscal policy falls squarely within the legislative domain. The approximately Rs310 billion in potential revenue safeguarded by this ruling underscores the financial stakes involved.
This ruling follows the 27th Constitutional Amendment, which consolidated tax-related cases under the FCC after numerous appeals from Sindh, Lahore, and Islamabad High Courts. Previously, businesses, banks, and individuals had contested the tax, initially introduced in 2015 by the PML-N government to fund rehabilitation efforts following Operation Zarb-i-Azb. The tax has evolved since then, with adjustments to income thresholds and rates, most notably in 2022.
Beyond the Billions: Implications for Future Tax Policy
The FCC’s ruling isn’t simply about validating an existing tax; it sets a precedent for future fiscal policy. Expect to see a more assertive approach from the government in implementing tax measures, knowing that judicial challenges based on broad interpretations of fairness or economic impact are less likely to succeed. This could lead to bolder tax reforms aimed at addressing Pakistan’s persistent revenue shortfall.
Did you know? Pakistan’s tax-to-GDP ratio remains one of the lowest in the world, hovering around 9-10%. This ruling could empower the government to implement measures to increase this ratio, potentially funding crucial development projects and social programs.
However, this doesn’t mean the government has a free hand. The FCC did provide some nuance, allowing oil and gas exploration companies to seek individual exemptions based on existing concession agreements. This demonstrates a willingness to consider specific circumstances while upholding the overall principle of parliamentary authority.
The Rise of Constitutional Courts in Fiscal Disputes
The increasing number of tax disputes landing in constitutional courts globally is a notable trend. This reflects a growing complexity in tax laws and a heightened awareness of taxpayer rights. In the United States, for example, challenges to tax legislation frequently end up before the Supreme Court. Similarly, in Europe, the European Court of Justice plays a vital role in interpreting EU tax directives.
Pakistan’s experience highlights the importance of a robust constitutional framework for resolving tax disputes. The 27th Amendment, transferring these cases to the FCC, was a proactive step towards ensuring consistent and authoritative rulings. This centralized approach avoids conflicting interpretations from different High Courts, creating greater legal certainty for businesses and taxpayers.
What’s Next for Pakistan’s Tax Landscape?
The FCC ruling is likely to spur further debate on tax equity and efficiency. While the court has affirmed Parliament’s right to legislate, it hasn’t addressed the underlying concerns about the fairness of the tax system. Expect increased pressure on the government to broaden the tax base, reduce exemptions, and improve tax administration.
Pro Tip: Businesses should proactively review their tax compliance procedures to ensure they align with the latest rulings and regulations. Seeking expert tax advice is crucial in navigating the evolving landscape.
The focus will likely shift to improving the FBR’s capacity to collect taxes and address tax evasion. Digitalization of tax processes, enhanced data analytics, and stricter enforcement measures are all likely to be prioritized. The government may also explore new revenue streams, such as carbon taxes or digital services taxes, to diversify its revenue base.
FAQ: Understanding the Super Tax Ruling
- What is the “super tax”? It’s an additional tax levied on high-income earners and certain profitable sectors, initially introduced to fund rehabilitation efforts.
- Why was the super tax challenged in court? Businesses argued it was retrospective, discriminatory, and amounted to double taxation.
- What did the FCC rule? The FCC upheld the validity of the super tax, reaffirming Parliament’s authority to legislate on taxation.
- What are the implications of this ruling? It empowers the government to implement tax measures with greater confidence and sets a precedent for future fiscal policy.
- Does this mean the government can impose any tax it wants? No. The FCC clarified that courts can interpret tax laws but cannot rewrite them, leaving the determination of tax policy to Parliament.
Do you have thoughts on this ruling? Share your perspective in the comments below!
Explore more articles on Pakistan’s business and economy on Dawn.com.
Keep reading