Singapore’s Stock Market Revival: Is ‘Greatness’ Within Reach?
Singapore’s stock market is showing promising signs of life, with key metrics hitting levels not seen in over a decade. Recent parliamentary discussions, sparked by opposition MPs Louis Chua and Jamus Lim, highlight both the progress made and the challenges that remain in achieving a truly robust and dynamic equities market. While a review group’s efforts are bearing fruit – evidenced by increased trading value and IPO activity – the question remains: is this a sustainable turnaround, or just a temporary bounce?
The Numbers Tell a Story of Recovery
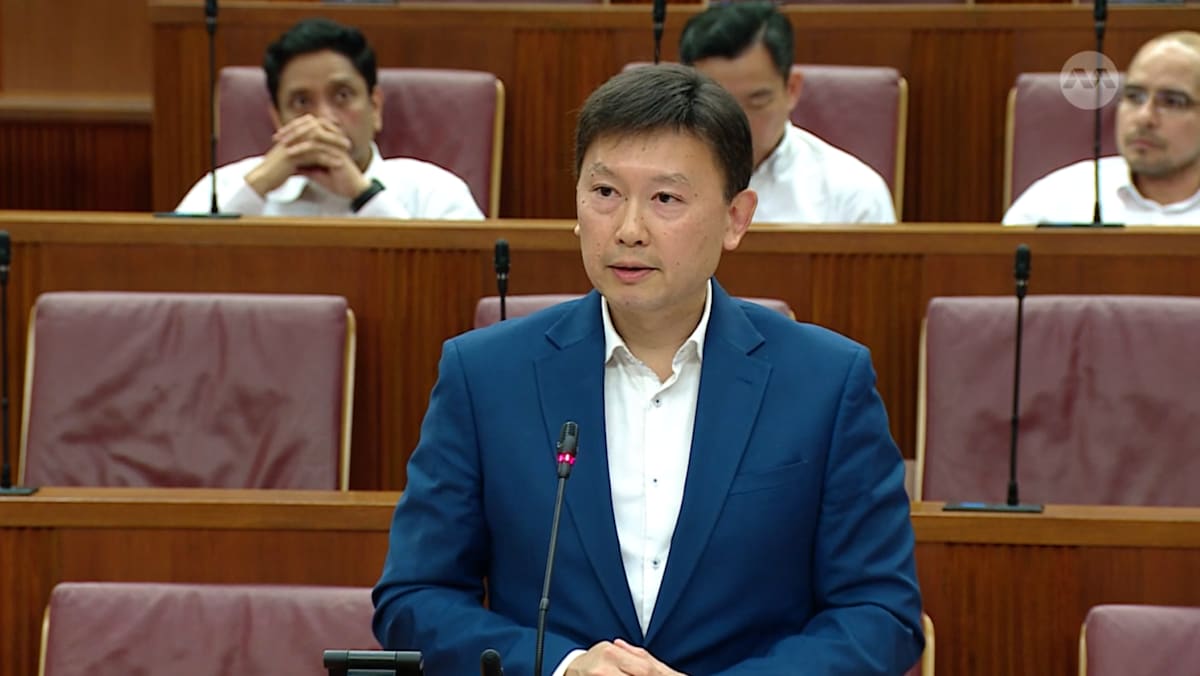
Minister for National Development Chee Hong Tat recently reported that the average daily traded value of securities in 2024 reached its highest point since 2010. A significant 40% increase saw 100 Singapore-listed stocks averaging over S$1 million in daily turnover. Furthermore, 2025 witnessed over S$2.4 billion raised through IPOs, the strongest showing since 2019. Crucially, the total market capitalization of listed companies surpassed the S$1 trillion mark. These figures demonstrate a clear upward trend, benefiting both large-cap and smaller, mid-cap companies.
However, raw numbers only paint part of the picture. The core debate, as articulated by Chua and Lim, centers on whether these gains are driven by fundamental improvements in company performance and investor confidence, or by external factors and short-term speculation.
The Push for Greater Accountability & Shareholder Returns
A key argument put forward by the opposition MPs revolves around the lack of mandatory requirements for Singaporean companies to demonstrate a commitment to improving shareholder returns. They point to Japan’s proactive approach, specifically the Tokyo Stock Exchange’s (TSE) structured disclosure framework. The TSE publishes monthly lists categorizing companies based on their disclosure status, creating what Chua describes as “constructive market pressure.”
This contrasts with Singapore’s current system, where the government is injecting significant capital – over S$5 billion through the Equity Market Development Programme – expecting returns, while listed companies face no equivalent compulsion to improve their fundamentals. This disparity raises concerns about the long-term sustainability of the market’s growth.
Did you know? Japan’s corporate governance reforms, initiated in the early 2010s, are widely credited with boosting shareholder value and attracting foreign investment. The TSE’s disclosure requirements were a central component of this overhaul.
Beyond Disclosure: Attracting Retail Investors & Fostering Innovation
The discussion extends beyond disclosure to encompass broader strategies for attracting local retail investors. Currently, a significant portion of trading volume is driven by institutional investors and foreign participation. Increasing retail participation could provide a more stable and diversified investor base.
However, attracting retail investors requires addressing concerns about accessibility, financial literacy, and risk management. Simplified investment platforms, educational initiatives, and robust investor protection measures are crucial. Furthermore, fostering innovation in the listing process – potentially through the introduction of dual-class share structures or streamlined regulatory pathways for high-growth startups – could attract a new wave of dynamic companies.
The Role of SPACs and the Future of Listings
The initial enthusiasm surrounding Special Purpose Acquisition Companies (SPACs) in Singapore has cooled. While intended to provide a faster and more efficient route to listing, SPACs faced challenges related to valuation, due diligence, and investor protection. The experience highlights the need for careful calibration of regulatory frameworks to balance speed and safeguards.
Looking ahead, Singapore is likely to focus on attracting high-quality companies in growth sectors such as sustainable technology, biotechnology, and financial technology (FinTech). The country’s strong regulatory environment, skilled workforce, and strategic location remain key advantages.
Pro Tip: Investors looking to capitalize on Singapore’s market growth should focus on companies with strong fundamentals, sustainable business models, and a clear commitment to shareholder value. Diversification is also key to mitigating risk.
What’s Next for the SGX?
The Monetary Authority of Singapore (MAS) and the Singapore Exchange (SGX) are actively exploring further enhancements to the equity market. These include initiatives to improve market liquidity, enhance trading infrastructure, and promote greater transparency. The success of these efforts will depend on a collaborative approach involving regulators, listed companies, investors, and market intermediaries.
The debate sparked by Chua and Lim is a healthy one, forcing a critical examination of the factors driving market performance and identifying areas for improvement. Achieving lasting “greatness” for Singapore’s equities market requires a long-term vision, a commitment to innovation, and a relentless focus on creating value for all stakeholders.
FAQ
Q: What is the Equity Market Development Programme?
A: It’s an initiative by the MAS to deploy over S$5 billion in capital to support the growth of the Singapore stock market.
Q: What are SPACs?
A: Special Purpose Acquisition Companies are shell companies that raise capital through an IPO to acquire an existing private company.
Q: Why is shareholder return important?
A: Strong shareholder returns indicate a healthy and well-managed company, attracting investors and driving market growth.
Q: What is the TSE?
A: The Tokyo Stock Exchange, known for its robust corporate governance standards and disclosure requirements.
Want to learn more about investing in Singapore? Explore our other articles on financial markets and investment strategies.
Related reading