Italy’s New Disaster Insurance Law: Shaping the Future of Business Resilience
Italy has recently passed a significant law mandating insurance coverage for businesses against natural disasters. This crucial legislation, designed to safeguard companies from the financial fallout of events like floods, earthquakes, and landslides, marks a pivotal shift in how Italy approaches disaster preparedness. As a seasoned observer of the insurance and business landscape, I’ve been following this development closely. Let’s unpack what this means for businesses and explore the potential future trends.
Key Provisions and Deadlines: What Businesses Need to Know
The core of the new law compels Italian businesses to secure insurance for damages arising from natural calamities. This insurance must cover both tangible assets (buildings and equipment) and the cost of business interruption in certain scenarios. The deadlines for compliance are staggered, providing a phased approach:
- Large Enterprises: Must comply by March 31, 2025.
- Medium-sized Enterprises: Deadline is October 1, 2025.
- Small and Micro Enterprises: Have until December 31, 2025, to get covered.
This phased implementation allows businesses to prepare adequately. There’s also a 90-day grace period where penalties for non-compliance are waived, allowing companies to arrange their insurance without immediate repercussions.
Did you know? This law is a direct response to the increasing frequency and severity of natural disasters worldwide. The aim is to enhance financial resilience among Italian businesses.
What’s Covered: Understanding the Scope of the Insurance
The mandatory insurance covers a wide range of potential damages. It is crucial for business owners to understand the breadth of coverage:
- Buildings: Coverage is based on the cost of rebuilding the structure.
- Movable Assets: Coverage is based on the cost of replacing them.
- Land: Coverage includes the cost to restore damaged terrain.
The law also includes provisions for buildings undergoing regularization, ensuring comprehensive coverage. Furthermore, in rental scenarios, the owner receives the indemnity with the obligation to reinvest it in property reconstruction.
Pro tip: Review your existing insurance policies. Make sure your coverage aligns with the new regulations and extends to all relevant assets.
Incentives, Oversight, and Market Dynamics
To encourage businesses to adopt broader coverage, the law includes incentives. For example, large companies that opt for a unified insurance policy covering their entire group can benefit from exemptions from deductibles up to 15% of the damage.
To maintain a fair insurance market, the Istituto per la Vigilanza sulle Assicurazioni (IVASS) and the price watchdog will monitor premium pricing. This is designed to protect both businesses and consumers from potential price gouging, which could arise from the mandatory insurance requirement.
Related reading: Learn more about IVASS and its role in regulating the insurance market here.
The Future of Disaster Resilience: Anticipating Trends
This new law is not just about mitigating immediate risks. It’s a building block for a more resilient economic future. Here are some trends we can expect to see emerge:
- Increased Demand for Insurance Products: Expect a surge in demand, particularly for specialized policies tailored to the specific risks of different industries and locations.
- Technological Integration: Insurance providers will likely adopt advanced technologies to assess risks more accurately. This includes using satellite data and AI to evaluate property vulnerabilities.
- Emphasis on Risk Prevention: Businesses will start focusing more on preventative measures, from strengthening infrastructure to developing robust business continuity plans.
- Greater Government Collaboration: We can anticipate enhanced public-private partnerships, with the government supporting disaster preparedness and recovery efforts.
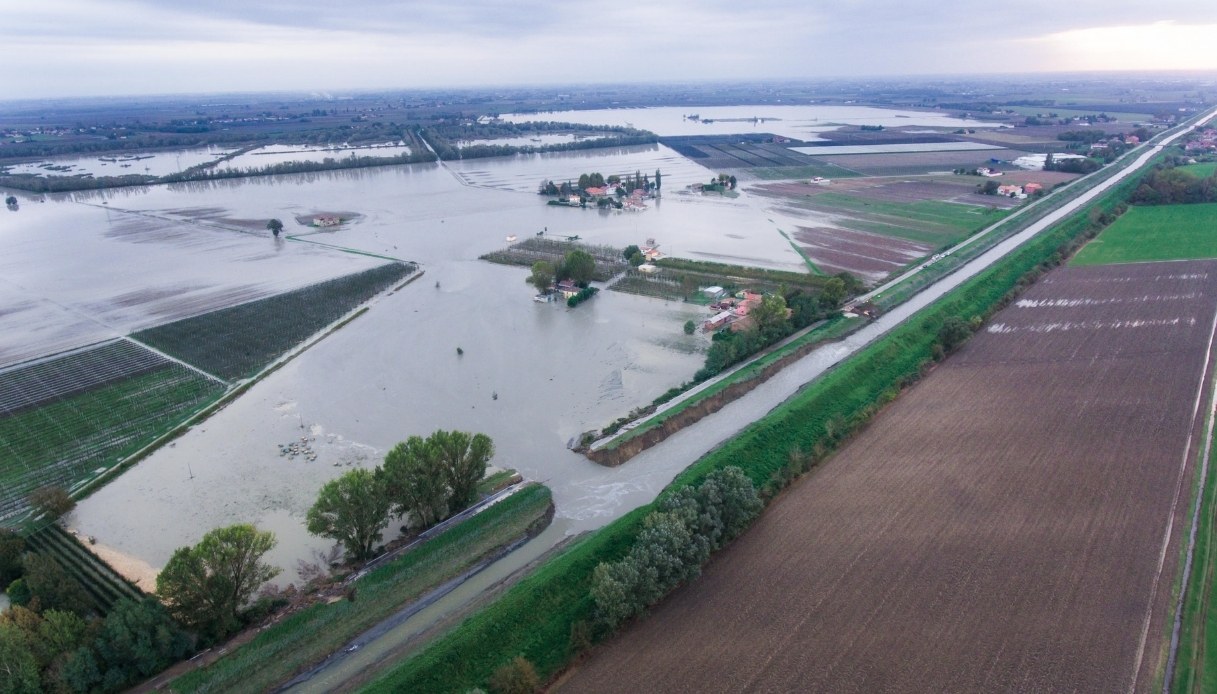
Case Study: Consider the impact of the recent Emilia-Romagna floods. Businesses with adequate insurance coverage were better positioned to recover, highlighting the importance of proactive risk management.
Frequently Asked Questions
Q: What types of natural disasters are covered?
A: The insurance covers events like earthquakes, floods, landslides, and other geological events.
Q: What happens if a business fails to comply?
A: Non-compliance may result in penalties, so it’s crucial to meet the deadlines.
Q: Does this law affect businesses of all sizes?
A: Yes, but the deadlines for compliance vary based on the size of the enterprise.
By adopting a proactive approach to insurance, businesses can fortify their financial future and contribute to a more stable economic landscape.