The Unexpected Healthcare Costs of Retirement: A Looming Crisis for Millions
For many, retirement signifies financial freedom and a well-deserved rest. However, a growing number of retirees are facing a harsh reality: healthcare costs, particularly health insurance premiums, can quickly erode their savings. The transition from employer-sponsored health plans to the regional national health insurance system is often a shock, with premiums potentially increasing significantly.
From Shared Costs to Full Responsibility
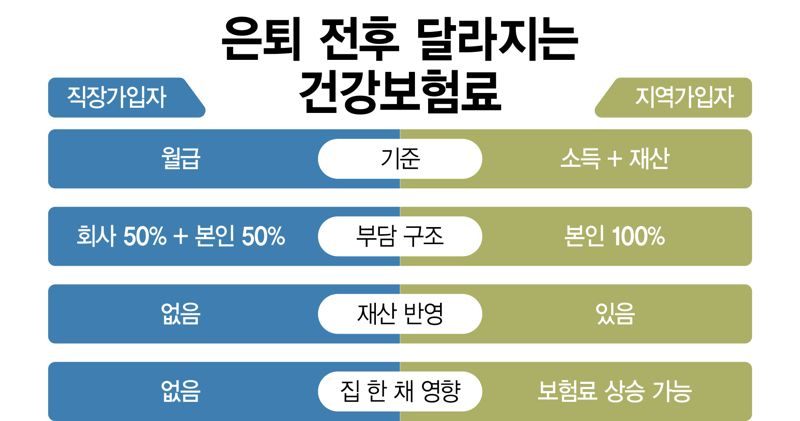
While employed, health insurance costs are typically shared between the employer and employee. Upon retirement, this changes dramatically. Retirees generally transition to the regional national health insurance system, where they become solely responsible for 100% of their premiums. This shift, coupled with a different calculation method, is the primary driver of increased costs.
How Regional Health Insurance Premiums Are Calculated
Unlike employer-sponsored plans based on salary, regional health insurance premiums are calculated based on income, property, and assets. This means that even retirees with no current income can face substantial premiums if they own a home or have significant savings. The system views assets as potential income, effectively charging retirees for their ability to pay, regardless of their actual earnings.
The calculation includes a ‘property score’ based on the value of owned land, housing, buildings, ships, and aircraft. Even rental or lease deposits are factored in, contributing to the overall premium.
The Impact of Property Ownership
For homeowners, this can be particularly problematic. A home, intended as a source of security in retirement, becomes a factor increasing healthcare costs. The value of the property, as assessed for property tax purposes, is used to determine a ‘virtual income,’ which is then used to calculate insurance premiums.
Navigating the System: Key Strategies for Retirees
While the system can seem daunting, there are strategies retirees can employ to mitigate the financial burden:
- Imun-gyeo Sok Gap (임의계속가입): Applying for continued enrollment within two months of retirement can allow retirees to maintain their previous employer-sponsored rates for up to 36 months.
- Skin-yangja (피부양자) Status: If eligible, registering as a dependent under a spouse or child’s employer-sponsored plan can eliminate premiums. However, strict income and asset limits apply.
- Financial Planning: Carefully manage financial assets and income streams to avoid exceeding income thresholds for dependent status.
- Utilize the National Health Insurance Service’s Simulation Tool: Estimate potential premiums based on individual circumstances.
Recent Changes and Their Limited Impact
Recent adjustments to the system, such as the elimination of automobile-related premiums and an increase in the basic property exemption, have provided some relief. However, the impact has been limited, particularly for those with substantial assets.
Understanding the Skin-yangja (피부양자) Requirements (2026)
Maintaining dependent status requires meeting specific criteria:
- Income: Annual income must be below 20 million won.
- Property Tax: Property tax assessed value must be below 540 million won. Between 540 million and 900 million won, income must be below 10 million won. Above 900 million won, dependent status is generally not possible.
FAQ: Common Questions About Retirement and Health Insurance
Q: Why did my health insurance premiums increase after retirement?
A: The calculation method changes. You transition from a shared-cost, salary-based system to a system based on your income, property, and assets, and you become responsible for 100% of the premium.
Q: What is the ‘Imun-gyeo Sok Gap’ option?
A: It allows you to continue paying your previous employer-sponsored rates for up to 36 months after retirement, but you must apply within two months of leaving your job.
Q: Can I become a dependent on my child’s insurance plan?
A: Yes, if you meet the income and asset requirements.
Q: Does my pension income affect my premiums?
A: Yes, public pensions (national and civil servant pensions) are included in the income calculation.
Pro Tip: Don’t wait until you retire to investigate your options. Start planning and simulating potential costs well in advance to avoid surprises.
The shift to regional health insurance can be a significant financial burden for retirees. Proactive planning, understanding the calculation methods, and exploring available options are crucial for ensuring a secure and comfortable retirement.
Explore more articles on retirement planning and financial wellness here.
Related reading