President Donald Trump issued a warning that certain levels of inflation could help rapidly reduce the national debt, unsettling Wall Street and driving the 10-year U.S. Treasury yield past a crucial 5% threshold.
The remark, delivered earlier this month, suggests the White House may tolerate rising consumer prices to devalue the national debt load, according to Yahoo. That stance collides directly with broader economic headwinds, including ongoing tariffs that have lifted average U.S. import levies to about 9.6% and a conflict in Iran that pushed Brent crude oil prices up 55% since the start of the year, as reported by FOOL.
Bond Market Yields Spike Past Five Percent
U.S. inflation currently sits at 3.7%, remaining well above the Federal Reserve’s 2% target and prompting the central bank to keep interest rates elevated. These high borrowing costs increase the expense for the government to refinance its $40 trillion debt mountain. International investors have responded by selling off U.S. debt, pushing the 10-year Treasury yield past the 5% psychological support level to its highest mark in more than two decades.
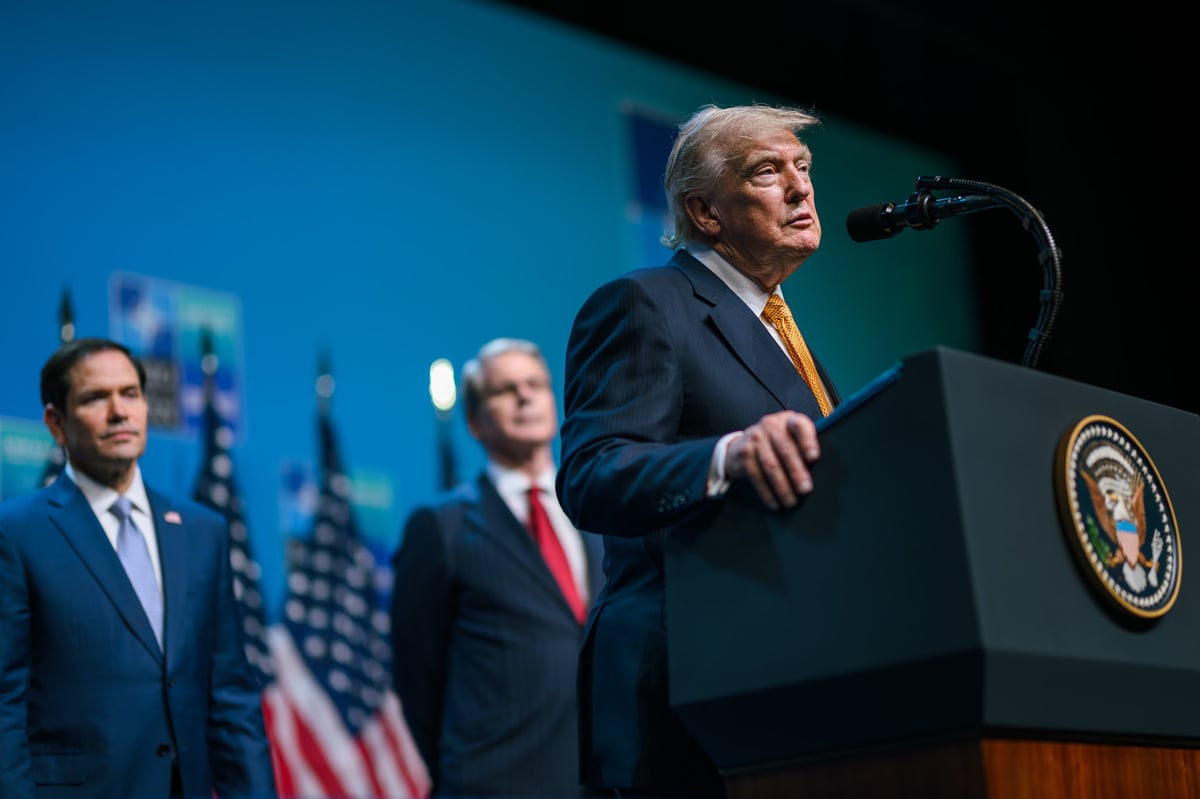
According to the International Monetary Fund, the U.S. will likely be unable to grow its way out of its current debt crisis. Despite these pressures, the administration requested a record $1.5 trillion military budget for 2027.
Technology Sector Drives Heavy Market Concentration
While the benchmark S&P 500 index has climbed over 39% since the inauguration in late 2024, market gains remain heavily concentrated. CME Group data shows the information technology sector now accounts for 40% of the S&P 500’s market capitalization. Pro-business policies, including the One Big Beautiful Bill Act—which cut corporate taxes, deregulated energy and technology projects, and permanently extended provisions from the 2017 Tax Cuts and Jobs Act—have sustained investor optimism.
During an interview with Time Magazine in October, the president remarked that elevated inflation could help pay down obligations very rapidly by devaluing the U.S. currency and the national debt. That logic indicates the administration may maintain inflationary fiscal policies over the coming years, presenting a risk to savers and fixed-income portfolios.
Recent midterm election results could impose checks and balances on government spending plans, such as the proposed $1.5 trillion military budget, and help calm the bond market. Meanwhile, the administration’s support for new energy projects and data center construction remains vital for the tech sector’s infrastructure buildout for generative AI. Yet fixed-income investors face distinct pressures. Inflation erodes real returns, turning the S&P 500’s 10% average annual return into a real return of 6.3% under a 3.7% inflation rate. Analysts suggest portfolio diversification across multiple asset classes remains the primary defense against potential downside risks.
Keep reading