Peru is entering a period of two months of electoral uncertainty as the country prepares for the second round of elections in June. This climate has led many to question whether now is the appropriate time to save in U.S. Dollars.
While analysts suggest that uncertainty regarding the next president could lead to a rise in the dollar’s exchange rate over the next two months, they warn against speculating on this possibility. Because a price increase is not guaranteed, using the currency as a tool for generating income through buying and selling is considered highly risky.
Risks of Currency Speculation
Juan Acosta, a professor of International Business at the UPC, warns that attempting to generate income through dollar fluctuations could cause a person’s funds to change drastically in a very short period.
Acosta emphasizes that the exchange rate is not solely influenced by the local electoral situation, but also by international factors. This combination makes it unpredictable to estimate future exchange rates, leading to his recommendation not to “bet” on the dollar to make a profit.
Strategic Uses for Dollar Savings
Despite the risks of speculation, experts identify specific scenarios where saving in dollars remains a viable strategy. Acosta notes that dollars can be used as part of an asset diversification strategy that does not depend on exchange rate variations.
Julio Cabrera, a finance professor at USIL, suggests that saving in dollars is appropriate when an individual has a planned future payment in that currency. This includes obligations such as paying off a dollar-denominated loan, funding international travel, or paying rent in dollars.
Alternative Saving and Investment Options
For those seeking lower risk, fixed-term deposits are highlighted as a primary option. According to data reported on May 5 by the Superintendencia de Banca, Seguros y AFP (SBS), banks are currently paying an average annual interest rate of 3.76% for deposits in soles and 2.55% for deposits in dollars.
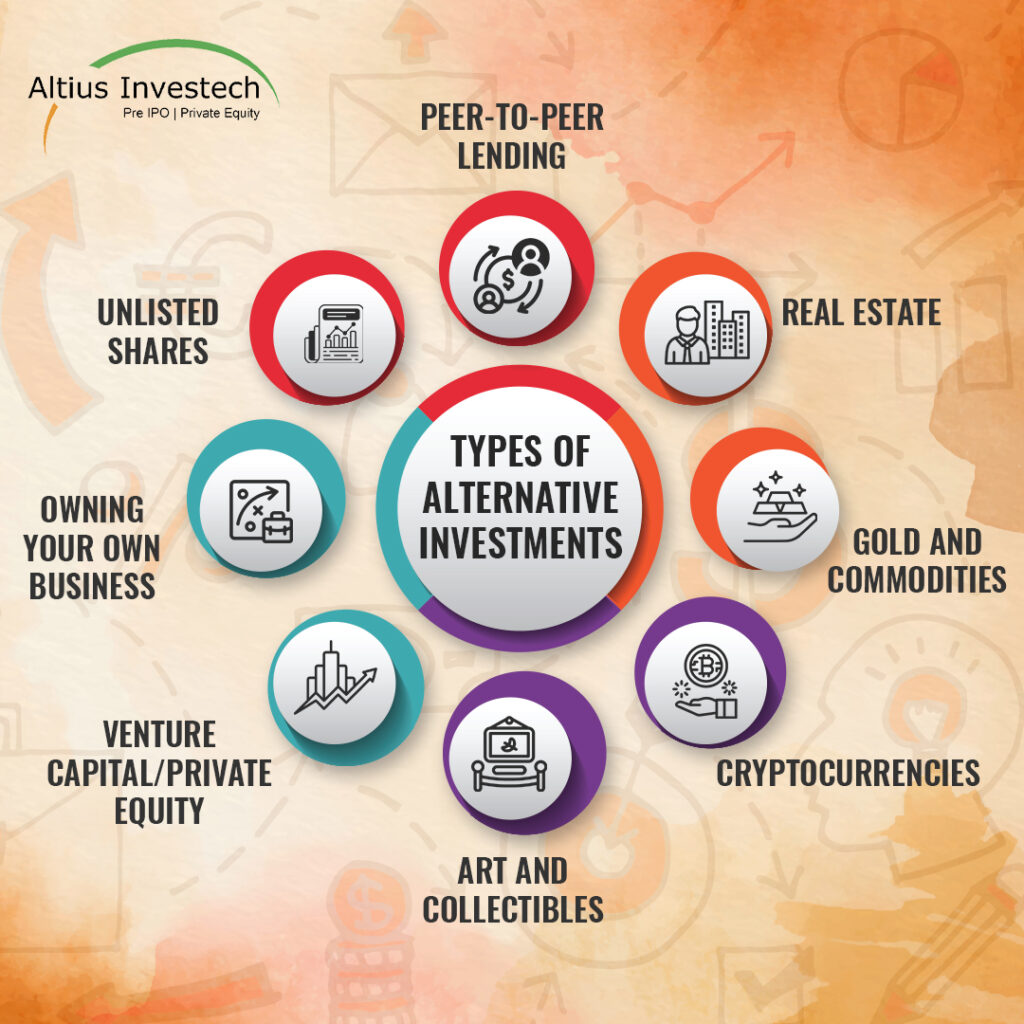
Other investment alternatives mentioned by Juan Acosta include:
- Mutual Funds: These depend on the performance of stocks or bonds.
- U.S. Stock Market: Investing in companies such as Apple, Amazon, or those linked to the field of artificial intelligence.
- AFP Voluntary Contributions: Non-pension contributions that offer the freedom to be withdrawn at any time and remain independent of the pension fund.
Frequently Asked Questions
Is it a solid idea to buy dollars to make a quick profit before the elections?
Analysts do not recommend this, as the rise of the dollar is not certain and speculating for income can be very risky, potentially causing funds to change drastically in a short time.
When is it specifically recommended to save in dollars?
It is recommended when it is part of an asset diversification strategy or when We find future obligations to be paid in dollars, such as loans, rent, or travel expenses.
What are the current interest rates for fixed-term deposits?
Based on SBS data from May 5, the average annual interest rate is 3.76% for soles and 2.55% for dollars.
How do you balance your savings between local currency and foreign assets during times of political uncertainty?
Worth a look