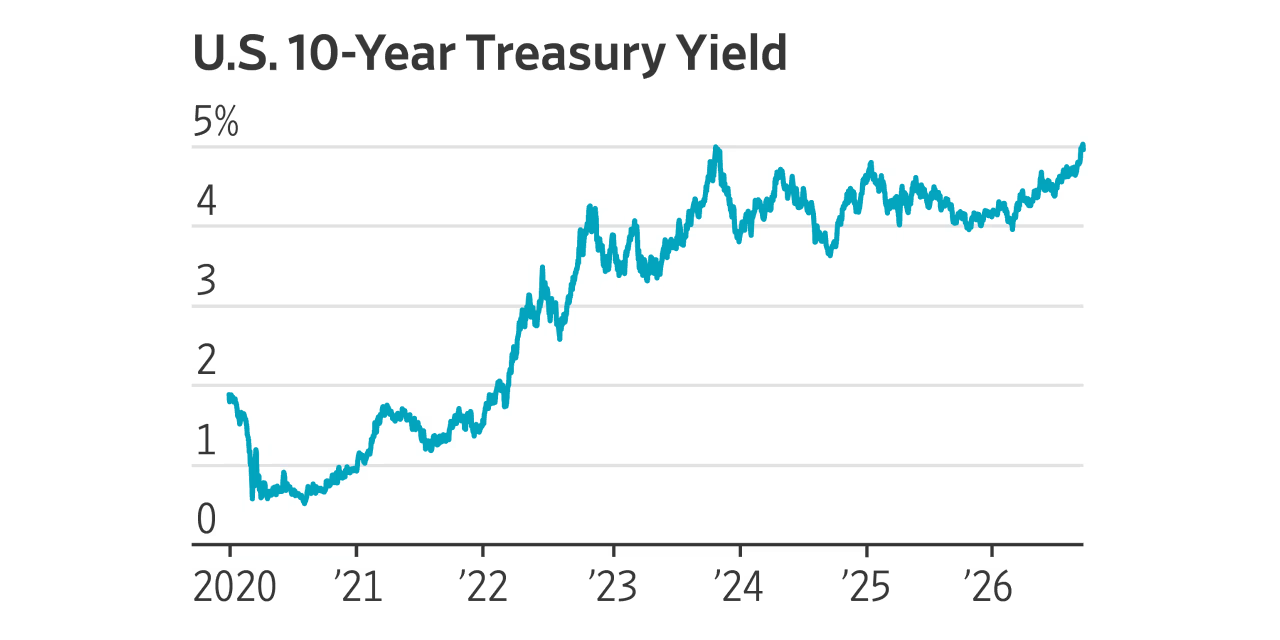
U.S. 10-year Treasury yields climbed above 5% on September 15, 2026, marking the highest level since 2007. The surge is driven by persistent inflation, rising oil prices, and investor demands for compensation on a $40 trillion federal debt burden, even as the Federal Reserve raised the federal funds rate by a quarter of a percentage point.
Federal Reserve Rate Decision and Surging Energy Costs
The bond market has faced sustained pressure from restricted global supply chains, geopolitical conflict, and massive government borrowing. First the pandemic and then war have restricted the supply of goods, pushing inflation higher. At the same time, government deficits have flooded the market with bonds and fueled consumer spending. These forces pushed the benchmark 10-year Treasury yield to a 19-year high above 5% in September 2026. The intraday milestone represents only the first time since 2007 that it closed at this level, with October 2023 being the most recent intraday occurrence. Federal Reserve Rate Decision and Surging Energy Costs
The move higher in yields coincided with a Federal Reserve policy meeting led by Kevin Warsh, where the central bank raised the federal funds rate by a quarter of a percentage point to a range of 3.75% to 4%, marking the first rate hike since July 2023. Despite that adjustment, investors had priced in separate expectations ahead of the FOMC meeting. Energy markets have added substantial upward pressure to inflation expectations. Crude oil prices climbed firmly above $100 per barrel amid ongoing supply restrictions tied to the Iran war that began in late February and a lack of a reopening timeline for the Strait of Hormuz, a critical oil passageway. Because these higher energy costs keep the Consumer Price Index above the central bank’s 2% target, the 30-year Treasury yield also touched 5.39% on Tuesday.
Weighing the Debt Burden and Bond Vigilantes
Beyond immediate inflationary concerns, structural fiscal pressures are forcing a reassessment of long-term risk. Investors are reacting directly to the nation’s immense fiscal obligations.
At the same time, investors are insisting on being compensated for high levels of government debt and the ever-rising deficit, TradeNation senior market analyst David Morrison said
David Morrison, senior market analyst at TradeNation, via Yahoo Finance
This sentiment reflects broader market anxiety over the sustainability of the $40 trillion federal debt burden. Treasury Secretary Scott Bessent has attempted to mitigate these pressures by implementing buybacks of long-dated Treasuries, an uncommon course of action historically, though these actions have not yet reversed the upward trend in yields. Meanwhile, strategists note that rising borrowing costs are a global phenomenon, with rates in countries such as Japan, the UK, and Germany also rising. In Japan, rising rates and a strengthening yen have contributed to the unwinding of the yen carry trade, in which investors borrow cheaply in Japan and invest in higher-yielding assets abroad.
Evaluating the Risks to Stock Portfolios and Corporate Borrowing
As benchmark borrowing costs rise—affecting everything from corporate debt issuance for artificial intelligence infrastructure to everyday mortgages—market observers hold sharply contrasting views on what this means for equity portfolios. Higher risk-free yields make fixed-income alternatives more attractive to capital, potentially drawing funds away from equities and putting downward pressure on high-growth stock valuations through elevated discount rates.

Even so, some analysts view the current environment through a historical lens.
US economic growth is impressive, and bond yields are only back to levels seen before the Great Financial Crisis, which was followed by an extraordinary period of financial repression from the Federal Reserve, Morrison said
David Morrison, senior market analyst at TradeNation, via Yahoo Finance
Carol Schleif on Elevated Yields Coming to Stay
Other financial professionals emphasize that while the climb has been orderly and has not happened overnight, this environment is likely to persist. Carol Schleif, chief market strategist at BMO Wealth Management, noted, Even though the rise in bond yields so far this year has been orderly, and it has not happened overnight, these elevated yields could be here to stay for some time.
Related reading