
Navigating the “Great Rotation” in AI Stocks
The investment landscape for artificial intelligence has entered a new phase. While AI stocks dominated headlines for years, the market experienced a “Great Rotation” away from the technology sector. This shift led to plunging share prices and pushed the tech-heavy Nasdaq Composite into correction territory.
For seasoned investors, these corrections often signal a transition from speculative hype to a focus on fundamental value. When sentiment shifts, the market tends to punish companies with high capital expenditures, even if those investments are critical for long-term dominance.
The High Cost of AI Leadership: Understanding Capex
One of the primary drivers of recent volatility has been the massive capital expenditure (capex) required to sustain AI growth. Microsoft, for example, saw its capex reach $37.5 billion in its fiscal second quarter ended December 31—a 66% year-over-year increase.
Why Infrastructure Upgrades are Non-Negotiable
The race for AI supremacy requires more than just software; it requires a massive physical overhaul of data centers. As the world’s second-largest cloud computing provider behind Amazon, Microsoft found that its existing infrastructure was no longer sufficient for the advanced capabilities required by modern AI systems.
This necessity for infrastructure upgrades justifies the high spending. The investment is already yielding results: in fiscal Q2, Microsoft’s cloud division sales grew 29% to $32.9 billion, contributing to a total revenue increase of 17% to $81.3 billion.
The Microsoft-OpenAI Power Dynamic
A critical component of the current AI trend is the symbiotic relationship between infrastructure providers and AI developers. OpenAI, the creator of ChatGPT, currently accounts for 45% of Microsoft’s remaining performance obligations (RPO).
While depending on a single customer for such a significant portion of RPO can be a concern for Wall Street, the growth trajectory of that customer is unprecedented. OpenAI’s revenue grew from $1 billion per quarter at the end of 2024 to $2 billion per month.
Evaluating Undervaluation in a Volatile Market
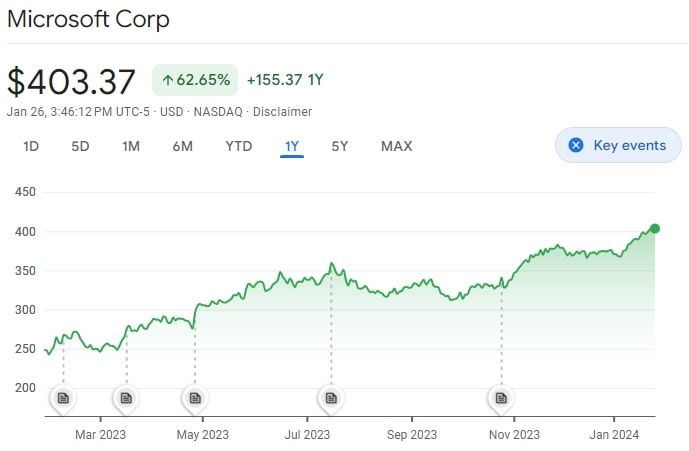
Despite the pressure on share prices—with Microsoft hitting a 52-week low of $356.28 on March 30—fundamental data suggests a disconnect between market price and company value. Morningstar has indicated that Microsoft looks 38% undervalued relative to a $600 fair value estimate.
Financial health remains robust. Net income for Microsoft jumped 60% to $38.5 billion in fiscal Q2 and gross margins increased by 16% year-over-year. This combination of surging net income and a depressed share price often creates a compelling entry point for long-term growth investors.
For those wary of tech volatility, some investors are diversifying into stocks that are sheltered from AI disruption to balance their portfolios.
AI Investment FAQ
Is the “Great Rotation” a sign that AI is failing?
No. This proves a shift in market sentiment and a rotation of capital away from the tech sector, often caused by concerns over high capital expenditures rather than a failure of the technology itself.
Why is Microsoft spending so much on capex?
Microsoft is upgrading its cloud infrastructure due to the fact that the previous technology is insufficient for the advanced requirements of AI systems. This is necessary to maintain its position as a leader in the AI race.
What is the projected growth of the AI market?
Industry forecasts project the AI market will reach $335 billion this year and grow to $1.3 trillion by 2032.
What is the risk of Microsoft’s relationship with OpenAI?
The primary risk is concentration, as OpenAI accounts for 45% of Microsoft’s remaining performance obligations (RPO). However, this is offset by OpenAI’s rapid revenue growth.
What are your thoughts on the current AI market correction? Are you buying the dip or looking for stocks sheltered from the volatility? Let us know in the comments below or subscribe to our newsletter for more deep dives into growth stocks.
Keep reading