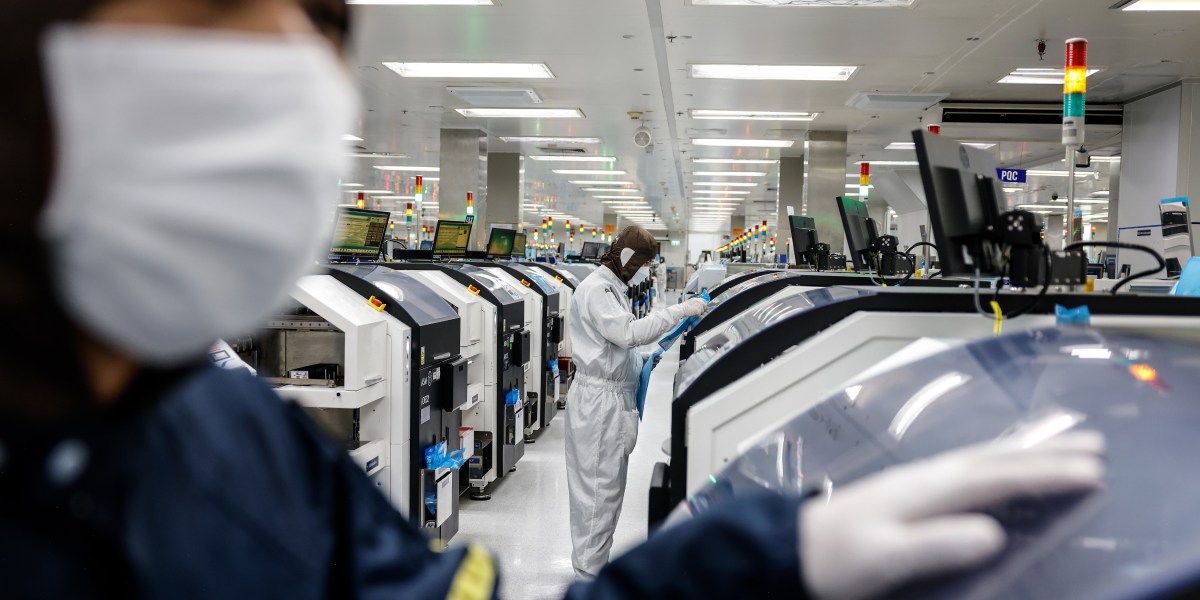
Southeast Asia has drawn billions of dollars in new manufacturing investment as global companies adopt a “China plus one” strategy, but the region is reaping conditional and uneven benefits that leave local ecosystems vulnerable to cheap Chinese imports. While Vietnam, Thailand, and Malaysia secured massive factory inflows as manufacturers pivoted away from rising costs and geopolitical tensions in China, economists and regional leaders warn that the gains are largely capped at low-skill assembly and assembly-line jobs rather than core component design and process know-how.
Vietnam and Malaysia Lead Regional Gains Amid Shifting Trade Flows
Vietnam has emerged as the star economy of Southeast Asia under the manufacturing shift, posting 8.0% GDP growth in 2025 compared to 7.1% in 2024, according to official economic data. Exports from Vietnam to the U.S. jumped 28.1% to $153.2 billion last year, up from $119.6 billion the prior year. Yet this final assembly model remains heavily reliant on intermediate inputs sourced from elsewhere; Vietnam’s imports from China climbed nearly 30% to roughly $183 billion over the same period.
Malaysia has carved a distinct niche in the semiconductor and data center sectors. Data center investments in Malaysia currently amount to nearly 18% of the country’s GDP, representing the highest share globally according to HSBC analysts. Homegrown chip design firm SkyeChip also completed a blockbuster IPO on the Bursa Malaysia stock exchange, surging 300% on its main market debut. Despite these milestones, Malaysian Foreign Minister Datuk Seri Mohamad Hasan cautioned during a United Nations General Assembly statement that the Global South risks becoming merely a destination for data centers while high-level decisions about artificial intelligence remain made elsewhere.
Fragmented Ecosystems Limit High-Value Manufacturing Across ASEAN
Meng-Chun Liu, director of the Chung-Hua Institution for Economic Research (CIER), notes that the traditional “flying geese” model—where lower-end manufacturing automatically cascades from advanced economies to less-advanced ones—is breaking down because China aims to retain full supply chains at home. Without mature local ecosystems, Southeast Asian factories must source raw materials, batteries, and optics from Chinese suppliers to keep production running. UCLA supply chain management expert Christopher Tang explains that while jobs are created in Southeast Asia, they remain largely low-skill assembly roles that cap the immediate creation of high-value industries.
Other countries are actively attempting to capture a larger share of the value chain through domestic industrial policies. Indonesia imposed a strict ban on nickel ore exports to force refining operations inside its borders, successfully attracting electric vehicle supply chain investments including car and battery manufacturing. Singapore continues to act as a regional hub for orchestrating supply chains and investments across the region, according to Goh Puay Guan, an associate professor at the National University of Singapore.
US Tariffs and Transshipment Scrutiny Complicate Regional Production
Washington’s trade policy has served as a primary catalyst for the “China plus one” shift, but it has also subjected Southeast Asian exporters to intense regulatory scrutiny. The White House released a report accusing 40 countries, including several in Southeast Asia, of engaging in a “transshipment scam” by diverting Chinese-made goods through alternative locations to evade U.S. tariffs. At the same time, the tariff differential between China and Southeast Asia has narrowed; following expanded Section 301 tariffs, goods from Singapore, Thailand, Vietnam, and the Philippines face a 12.5% duty, while Cambodia, Indonesia, and Malaysia face 10%. China faces an average tariff rate of 21%, though ongoing bilateral talks between Washington and Beijing pursue $30 billion in tariff reductions on non-sensitive goods like furniture and toys.
Did you know? When the U.S. tariff gap between China and Vietnam narrowed for notebook computers, several major PC brands moved production lines directly from Vietnam and Thailand back to China, according to Meng-Chun Liu.
To survive in a multipolar trade environment, Christopher Tang suggests that Southeast Asian nations may need to explicitly divide their industrial parks by establishing one vertically integrated supply chain compliant with Western standards alongside a separate network aligned with Chinese markets serving the Global South.
Influx of Cheap Chinese Goods Threatens Local Industries
Beyond export assembly challenges, Southeast Asia now confronts the prospect of absorbing excess manufacturing capacity from China as Chinese firms increasingly view the region as a consumer base rather than a labor pool. Trade between China and ASEAN surpassed $1 trillion for the first time in 2025, driven by China’s rising exports amidst domestic consumption slumps. Queen Mary University of London professor Lee Jones warns that this long-term trend may accelerate premature deindustrialization across Southeast Asia, carrying serious implications for regional economic growth and social stability.
Thailand’s national GDP growth has already slowed to 2%, pressured by an influx of competitively priced Chinese electric vehicles and consumer goods. Krungsri Research economist Supasyn Itthiphatwong noted in a research report that U.S. tariffs and Chinese retaliatory duties have flooded the Thai domestic market with cheap goods, intensifying price competition for local producers. For less-developed economies in ASEAN such as Cambodia, Laos, and Timor-Leste, the primary risk is not just outcompeting existing local producers, but rather that emerging domestic manufacturers never get a chance to take flight.
Frequently Asked Questions About Southeast Asia's Manufacturing Industry
Why are major brands moving some supply chains back to China from Southeast Asia?
Companies like Target have shifted certain supply chains back to China due to an underdeveloped factory ecosystem in Southeast Asia and a narrowing tariff gap between China and manufacturing hubs like Vietnam and Thailand for specific electronics.
How much did Vietnam’s exports to the United States grow recently?
Vietnam’s exports to the U.S. jumped 28.1% to $153.2 billion last year, rising from $119.6 billion the previous year, while the country’s overall GDP grew by 8.0% in 2025.
What is the risk of China’s export strategy for Southeast Asian economies?
Experts like QMUL professor Lee Jones warn that a flood of cheap Chinese consumer goods and electric vehicles could accelerate premature deindustrialization across Southeast Asia, undercutting local producers and threatening regional economic stability.
Worth a look